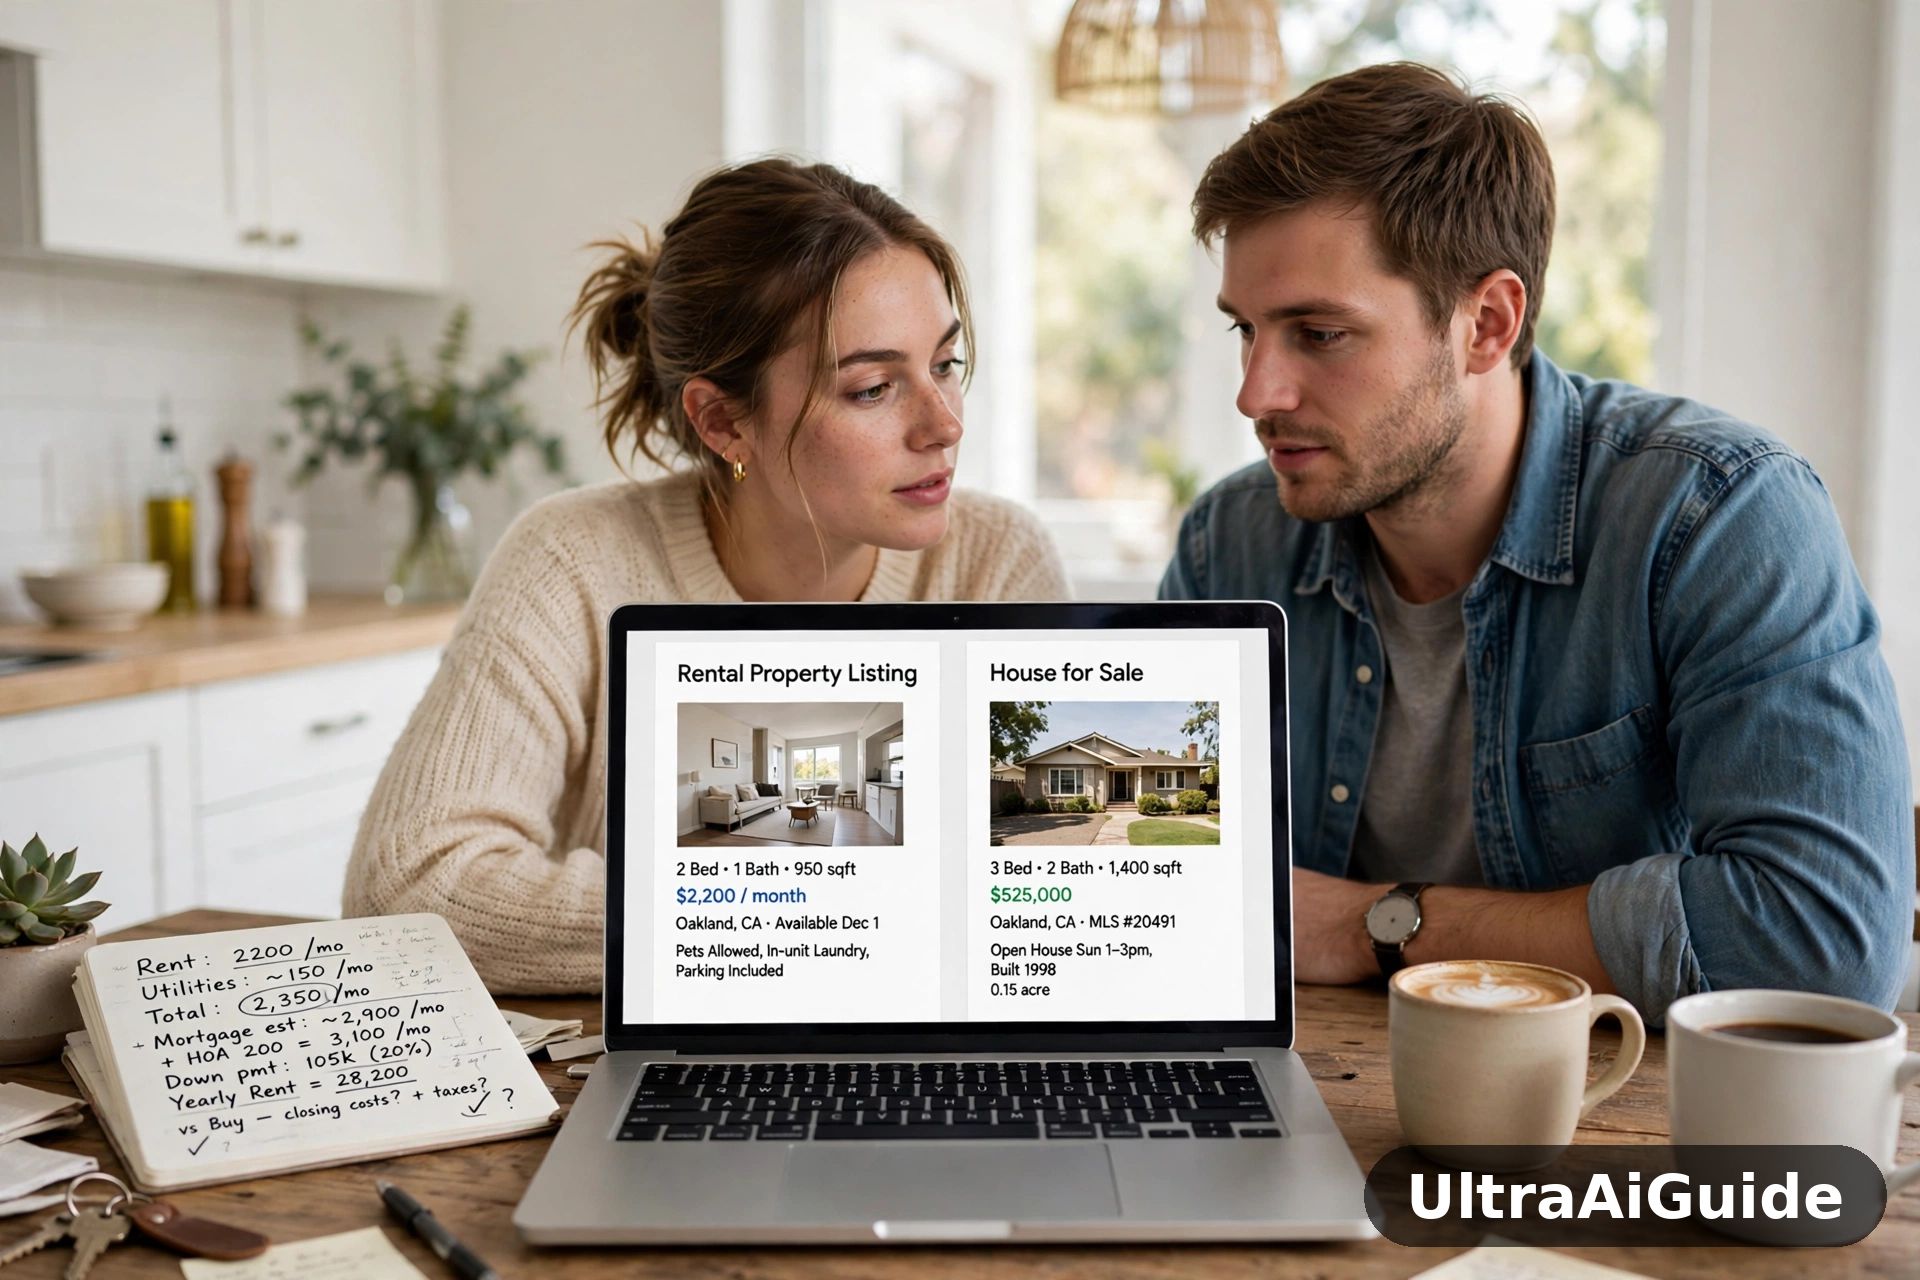
The renting vs buying question is usually argued as a matter of identity, landlords versus owners, when it is really a matter of arithmetic and timing. The right answer depends on your deposit, your likely stay and your local prices.
Renting buys flexibility and freedom from repair bills. Buying buys stability and a slow claim on an asset, at the price of a deposit, fees and responsibility for everything that breaks. Neither option is automatically the wiser choice.
This guide compares the two honestly: upfront and monthly costs, the role of time, what equity really means, and the situations where each option genuinely wins, so you can run the decision on your own numbers.
Renting vs Buying: The Short Answer
If you will probably move within about three years, renting usually wins, because buying costs thousands in fees that a short stay cannot repay. If you expect to stay five years or more, buying usually pulls ahead, provided the mortgage stays affordable.
Between those poles, the answer turns on the local gap between rents and mortgage payments, and on whether you can raise a deposit without emptying your savings. The sections below unpack each factor in turn.
The Upfront Costs Compared
Buying asks for far more cash before you get the keys. Renting asks for a deposit and the first month, and that difference alone settles the question for many households:
| Cost | Renting | Buying |
|---|---|---|
| Deposit | Capped at five weeks’ rent in England for most tenancies | Typically 5% to 20% of the purchase price |
| Professional fees | Minimal; a holding deposit at most | Conveyancing, survey, valuation and mortgage fees |
| Tax | None | Stamp duty may apply, depending on price and buyer status |
| Moving in | Furniture optional from day one | Furniture, appliances and any immediate repairs |
The Monthly Costs Compared
Rent is a single payment that covers the building, the repairs and the landlord’s costs and risks. A mortgage payment covers only the loan; the owner also pays buildings insurance, maintenance and, on flats, service charges on top.
Comparing rent with a mortgage payment alone therefore flatters buying. The fair comparison is rent against the full monthly cost of owning, including a realistic allowance for repairs, which older homes make especially hard to dodge.
How Long You Stay Changes Everything
Buying front-loads its costs: fees, duty and moving expenses all land in the first months, while renting spreads its costs evenly. That is why the length of your stay is the single biggest variable in the whole comparison.
A useful exercise is to find your break-even point: the stay at which the total cost of buying, minus the equity you would hold, drops below the total rent you would have paid. Work it through with your own figures rather than anyone else’s averages.
What You Build When You Buy: Equity
Each mortgage payment splits into interest and capital. Early payments are mostly interest, but over time the capital share grows, and any rise in the home’s value accrues to you rather than to a landlord.
Equity is not a guaranteed profit. Prices fall as well as rise, and the UK House Price Index has recorded level or falling periods in every region at some point. Treat equity as a long-term tendency, not a promise.
What You Keep When You Rent: Flexibility
Renting keeps your life portable. A new job in another city, a relationship change or a growing family can be answered within a notice period, not a sales chain. For people whose next few years are unsettled, that freedom carries real cash value.
Renters also keep their savings liquid and spread around rather than concentrated in one building on one street. That is easy to underrate until an owner needs to move quickly and discovers how slow a property can be to sell.
Maintenance, Repairs and Who Pays
When a rented boiler fails, the landlord pays; when an owned boiler fails, you do. Roofs, windows, appliances and pipework all follow the same rule, and one major repair can erase a year of the supposed savings from buying.
Tenants are not powerless in this arrangement. Knowing your rights as a tenant around repairs, deposits and notice periods is part of renting well rather than renting passively, and it costs nothing to learn them before you sign.
The Deposit Problem: Saving While You Rent
The hardest part of buying is often not the mortgage but the deposit, which usually has to be saved out of the same income that pays the rent. That double burden is why the typical first purchase now happens later in life than it once did.
Schemes and savings accounts exist to help, and their rules change over time, so check the current terms before relying on any of them. What does not change is the maths: a larger deposit usually unlocks cheaper mortgage deals and smaller monthly payments.
How Mortgages Actually Work, in Brief
A mortgage is a loan secured on the home itself. Most buyers choose between fixed rates, which hold payments steady for a set period, and variable rates, which can move up or down. Rates and products change constantly, so any figure you are quoted has a shelf life.
Lenders test affordability against higher rates than the one you would start on, and they look closely at the loan-to-value ratio: the share of the price you are borrowing. Independent guidance such as MoneyHelper’s mortgage guide explains the options without selling any of them.
When Renting Is the Smarter Move
Renting is usually the stronger choice when:
- Your work or your plans could move you within the next few years.
- Your deposit would leave you with no emergency savings at all.
- Local prices are high relative to rents, so owning costs far more each month.
- You are still deciding where, or with whom, you want to live long term.
When Buying Pulls Ahead
Buying tends to win when:
- You expect to stay put for five years or more.
- Mortgage payments on a suitable home sit close to local rents.
- You hold a deposit plus a separate cushion for fees and early repairs.
- Stability matters more to you than the freedom to move quickly.
Frequently Asked Questions
Is renting just throwing money away?
No. Rent buys housing, flexibility and freedom from repair bills, exactly as a hotel bill buys a room. The honest comparison is total cost over your likely stay, not whether one payment builds equity in isolation.
How big a deposit do I need?
Some mortgages start at 5% of the price, but larger deposits usually access lower rates. The right figure is the one that still leaves you an emergency fund after fees, moving costs and essential furniture are paid.
Can I buy if I might move for work?
You can, but a move within a few years makes the buying fees hard to recover. Some owners let the property out when they move, which needs lender consent and turns you into a landlord, with tax and legal duties attached.
Should I wait for prices to fall?
Timing the market is unreliable, and published price indices move slowly and are revised after the fact. A home you can afford, in a place you want to stay, at a fair current price is a sounder basis than any forecast.
Conclusion
Renting and buying are tools, not identities. Renting wins on flexibility and low commitment; buying wins on stability and long-term equity, once you stay long enough for its upfront costs to fade into the past.
Run your own numbers, over your own likely stay, in your own town. That calculation, repeated honestly, will tell you more than any general argument about which tenure is supposed to be better.